Yangzijiang Maritime linked to 4+2 Kamsarmax order
Reported orders at China’s Jiangsu Watts would extend the Singapore-listed investor’s bulker portfolio as it combines newbuilding commitments with vessel resales and chartering opportunities.
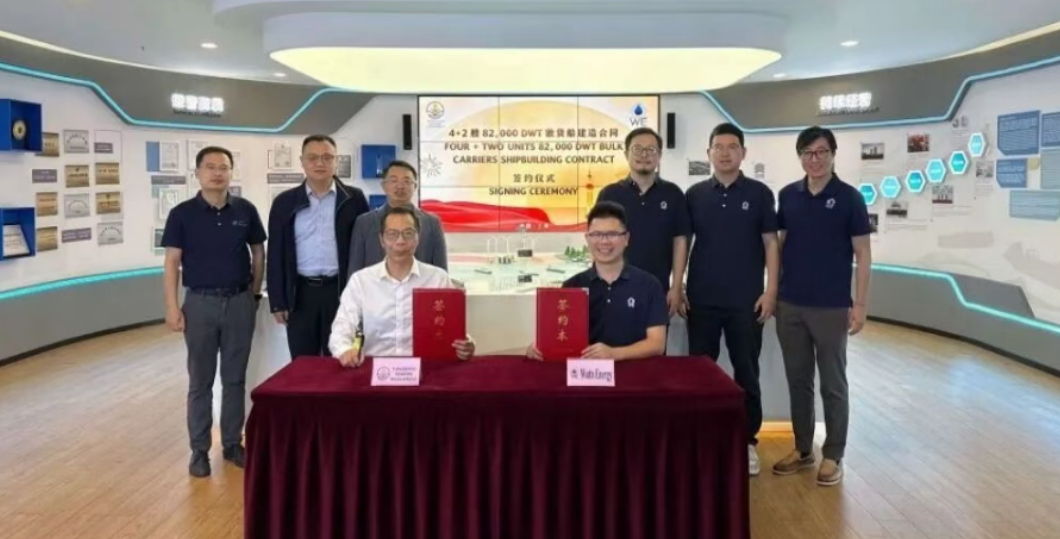
Yangzijiang Maritime Development has been linked to an order for up to six 82,000-dwt Kamsarmax bulk carriers at Jiangsu Watts Energy & Engineering, potentially adding another vessel class to its expanding maritime investment portfolio.
An October 12 report by Chinese industry publication iMarine, citing market information, described the transaction as four firm vessels plus two options. Prices and delivery dates were not disclosed, and the deal remains unconfirmed in public company announcements.
The reported move follows a series of investments spanning bulk carriers, product tankers, chemical tankers and very large crude carriers. Alongside those commitments, Yangzijiang Maritime has been signing resale contracts for vessels still under construction, seeking to release capital for further investment.
Expanding across vessel classes
Spun off from Yangzijiang Financial Holdings, Yangzijiang Maritime operates as a maritime investment and financing business. Its activities include acquiring vessel interests, financing shipping assets and arranging commercial employment.
Its dry bulk investments predate the latest ordering programme. In 2023, the group established a joint venture with Cetus Maritime to acquire eco-design Handysize vessels for deployment in the operator’s commercial pool.
The scale and breadth of its newbuilding commitments have since increased.
On September 18, the company announced 24 additional firm orders at Chinese yards for delivery between 2028 and 2030. These comprised six 64,500-dwt bulkers, six 49,800-dwt product/chemical tankers, eight stainless-steel chemical tankers of 28,000–29,000 dwt, and four 319,000-dwt crude tankers.
That programme is to be funded through a combination of equity co-investment and debt financing.
The announcement also disclosed 16 options, bringing the company’s newbuilding portfolio to 98 vessels: seven delivered ships, 75 firm vessels under construction and 16 optional units. Some projects had already been contracted for resale. The figure therefore covers investments at different stages, including options and assets committed to buyers.
An entry into the 82,000-dwt segment would extend its bulker exposure beyond the smaller ships featured in those earlier investments, potentially widening its access to buyers and charterers.
Resales support capital recycling
Recent disposals show how vessel sales fit into that expansion.
On August 6, Yangzijiang Maritime announced contracts to sell four approximately 40,000-dwt newbuilding bulkers, scheduled for delivery between April 2027 and May 2028.
The company said it had signed sale contracts for 12 newbuildings over the preceding nine months, with an aggregate gross value of about $500 million. That amount represents contracted sales value; earnings recognition and cash receipts depend on completion and delivery.
Some transactions have already progressed to handover. The first of four medium-range tankers covered by a sale agreement announced in November 2025 was delivered to its buyer on July 30, 2026.
Selling before delivery can shorten the period for which an investor remains exposed to a vessel’s operating market. Retaining and chartering a ship offers a different return profile, with recurring income and the possibility of a later sale.
For Yangzijiang Maritime, expanding across vessel classes creates more opportunities to choose between those routes. It also makes the timing of construction payments, deliveries and sale proceeds increasingly important to the pace of reinvestment.
Seeking an advantage at emerging yards
The company’s choice of builders is central to its investment approach.
In its first-half 2026 presentation, Yangzijiang Maritime outlined a strategy of working with second- and third-tier Asian yards, securing competitively priced construction slots and supporting projects through technical teams, repeat vessel designs and major-equipment procurement.
Its stated exit routes include presales, resales and charter employment.
That model helps explain the commercial appeal of builders expanding into mainstream merchant vessels. An investor with technical expertise and access to shipping customers may be able to connect available yard capacity with international demand.
The reported Watts transaction has not disclosed whether Yangzijiang Maritime would provide procurement, technical-management or financing support.
For Watts, the potential contract would build on an earlier entry into the same bulker segment. Industry reports in August linked the yard to four 82,000-dwt vessels for Xiamen-based Amoysailing Maritime, with delivery expected in 2028.
A further customer for comparable ships could support repeat production and more consistent procurement. The commercial value of that continuity will depend on construction quality and delivery performance, both of which influence a vessel’s acceptance by future buyers and charterers.
A growing orderbook raises the stakes
The investment programme is developing against a larger forward supply of bulk carriers.
In its October 5 market report, shipbroker Xclusiv put the dry bulk orderbook at approximately 15% of the existing fleet by deadweight, up from about 8% at the end of 2023. The Panamax/Kamsarmax segment stood at 13.1%.
For an investor relying on both resale opportunities and charter income, that supply outlook makes entry price and delivery timing particularly consequential. A competitively priced ship can provide a margin of protection, but returns still depend on its eventual sale value, employment and financing costs.
The reported Kamsarmax order would extend an investment strategy already visible across Yangzijiang Maritime’s bulker and tanker commitments. Its commercial significance will become clearer when pricing, delivery schedules and any resale or charter arrangements emerge.
READ MORE
 Dry Cargo
China Merchants Signs $2.8 Billion-Plus Simandou Shipping Deal
 Dry Cargo
Seaspan Enters Newcastlemax Market, with Yangzijiang Set to Build Two Tri-Fuel Ore Carriers
 Dry Cargo
Shipowners Bet on Ultramaxes: 42 Ships for Chinese Yards, Deliveries Stretch into 203
 Dry Cargo
Black Sea Wheat Loadings Plunge 78% as Grain Trade Reroutes
 Dry Cargo
“We Are Buying Ships”: Why Dry Bulk Is Beating Expectations
 Dry Cargo
40 Days from Brazil to China: COSCO SHIPPING Bulk’s New Grain Fleet Takes Shape
 Dry Cargo
Wooyang orders four triple-fuel Newcastlemax bulkers at China’s New Times for Vale contracts
 Dry Cargo
Shipowners Are Raising Capital to Buy Ships Again: Safe Bulkers Signals Dry Bulk’s Shift from Freight Recovery to Asset Expansion
 Dry Cargo
NORDEN Shows Why Ships Alone Are No Longer Enough
 Dry Cargo