How Much Longer Can Dry Bulk Stay Strong?

Buying a ship and operating one require different calculations in today’s dry bulk market.
Asked whether he would invest further in Kamsarmax bulk carriers, William Fairclough , Managing Director of Wah Kwong Maritime Transport Holdings Limited , offered a cautious assessment. Freight fundamentals remained supportive and the fleet was ageing, but asset prices had already risen substantially. At those entry costs, Wah Kwong leaned towards operating tonnage, while considering sales of existing vessels to capture some of their increased value.
Yet the company had continued investing. Fairclough subsequently disclosed that Wah Kwong had approximately 16 Ultramax newbuildings on order and was exploring longer charters for some vessels ordered several years earlier. Selling older ships, exercising caution over current prices and investing in new tonnage were all taking place within the same business.
Those choices frame a central question for dry bulk investors. Owners see support from both cargo demand and fleet supply, but strong earnings have also made ships expensive. How should they participate: acquire assets, charter in capacity, or secure longer employment for investments already made?
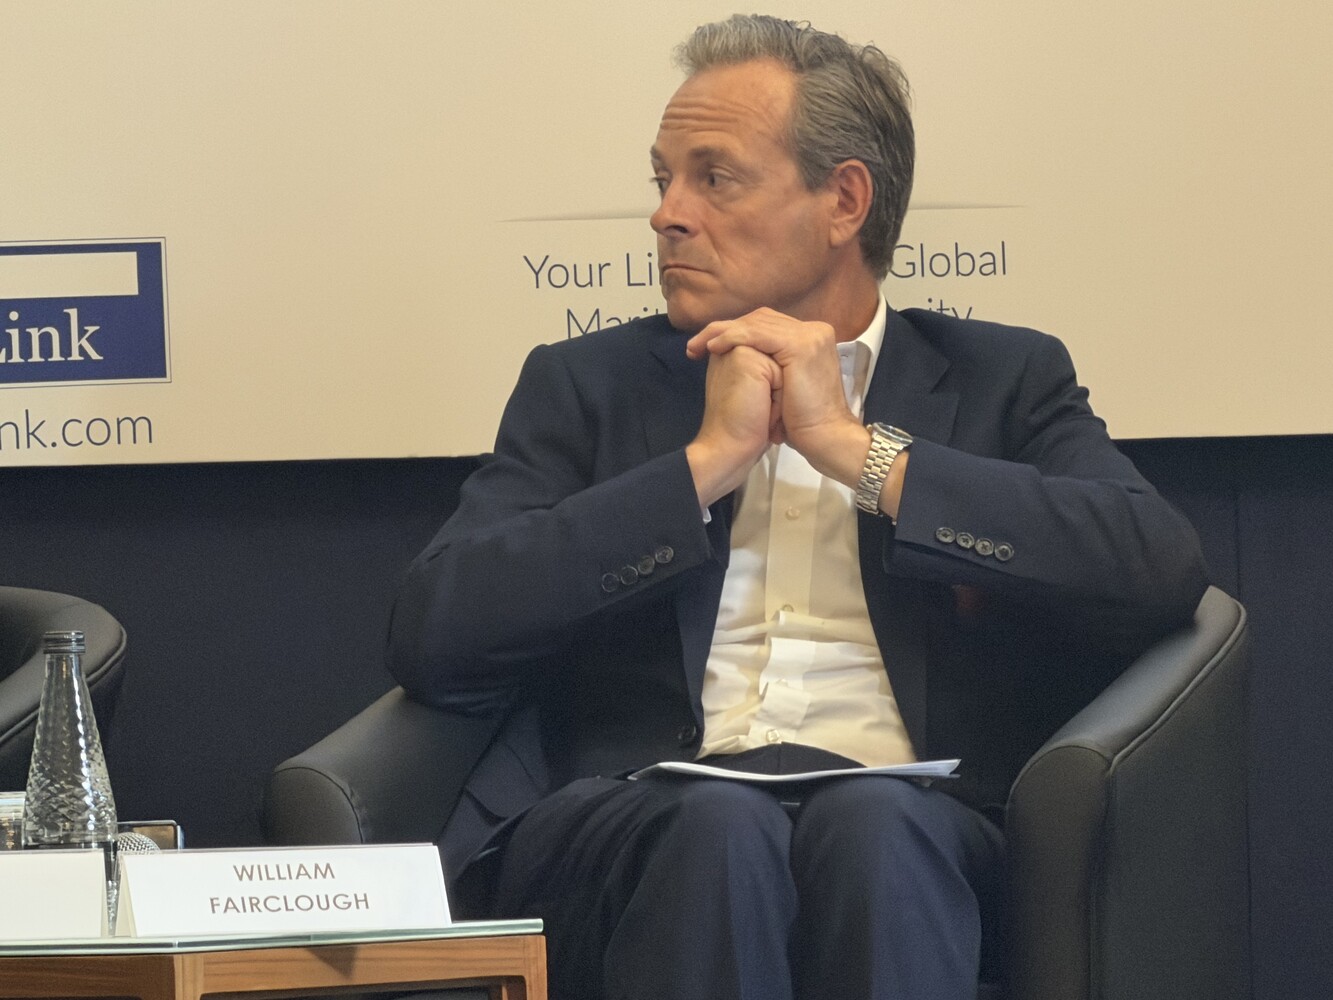
At the 18th Capital Link Shipping & Marine Services Forum in London on 15 September, shipowners, operators and a major cargo interest approached that question from different directions. Their discussion revealed a market supported by changing cargo flows and reduced transport efficiency, alongside investment decisions increasingly shaped by vessel type, entry price, delivery date and employment strategy.
Limited Ordering Meets Lower Transport Efficiency
Fairclough placed the current market in the context of a much longer cycle. The severe downturn of 2016 left a lasting impression on dry bulk owners. Even as conditions recovered, the experience influenced their willingness to order. The pandemic and geopolitical uncertainty further complicated decisions, contributing to an extended period of relatively restrained newbuilding investment.
Successive wars, weather disruptions and changes in trading patterns then absorbed effective capacity from that fleet. In Fairclough’s assessment, the present market reflected the combination of earlier underinvestment and the growing inefficiencies imposed on the transport system.
@Khalid Hashim, Managing Director of Thailand-listed dry bulk owner Precious Shipping Public Company Limited , took a particularly positive view of the supply outlook. Comparing the ageing fleet with the forward orderbook, he argued that a substantial share of new deliveries would be needed for replacement. On that basis, he believed dry bulk could continue to enjoy favourable conditions over the next four to five years.

Hashim also offered a self-deprecating explanation for the sector’s investment restraint. It had not resulted entirely from owners’ superior understanding of the cycle. Other shipping sectors had prospered and occupied shipyard capacity, limiting the opportunities available to dry bulk owners.
Karim Coumine , Head of Commercial Shipping for Minor Bulk and Panamax at mining group Anglo American , confirmed the constraint from a cargo owner’s perspective. Shipyards had favoured more complex, higher-value projects, pushing bulk carrier delivery opportunities towards the end of the 2020s and into the early 2030s. Recognising additional transport requirements did not mean a charterer could quickly access a new fleet.

Coumine nevertheless added a qualification: the orderbook was growing, and shipping had ample cash available for investment. Limited supply supported the immediate market, while continued ordering could change the balance further ahead.
The distinction matters when assessing fleet replacement. An orderbook similar in size to the older fleet does not guarantee that deliveries will be offset by demolition. Ships over 20 years old may continue trading, and an owner selling an older vessel may simply transfer it to another operator. Global supply ultimately depends on deliveries, recycling, speed, maintenance downtime and commercial availability together.
China’s Changing Cargo Flows Challenge Familiar Assumptions
The demand discussion soon returned to China.
Property activity, crude steel output and iron ore consumption have long been central to dry bulk analysis. Their explanatory power becomes less complete when industrial demand, raw material sourcing and export destinations are changing simultaneously.
Fairclough observed that movements in Chinese pig iron and crude steel production did not always correspond with changes in iron ore imports. Domestic ore supply, ore quality, procurement decisions and inventories could all influence import requirements. Coumine added the perspective of a miner and cargo interest: demand for higher-quality iron ore and pellet feed was also changing sourcing patterns and the associated transportation task.
Their observations point towards a broader way of assessing demand. Steel output matters, as do the origins of the raw materials and the destinations of the finished products.
Coumine described Chinese steel supporting infrastructure and industrial projects overseas, including in Africa and South America. Weakness in particular domestic markets therefore did not automatically imply a corresponding decline in all related shipping demand. Steel exports, overseas projects and industrial investment in other economies continued to generate cargoes.
China’s National Bureau of Statistics reported steel exports of 119.02 million tonnes in 2025, up 7.5% from the previous year. That scale underlines the importance of examining raw material imports and finished steel exports within the same assessment of trade flows.
For geared bulk carrier operators, these changes already influence everyday business. Hashim said steel represented a substantially larger share of Precious Shipping’s cargo mix than the average for comparable vessels. Changes in Chinese production and exports directly affected its cargo opportunities, trading routes and fleet choices.
Demand originating in China also reaches different vessel segments through different channels. Iron ore and bauxite imports are particularly important to larger bulk carriers. Steel, grain and other minor bulks are distributed across smaller vessel categories according to parcel size, port conditions and trading routes. A single assessment of Chinese demand cannot fully describe all of those markets.
Bauxite Is Already Delivering; Simandou Is Still Ramping Up
Fairclough placed particular emphasis on bauxite.
He argued that the attention paid to Chinese steel and property could obscure the transport demand emerging from the aluminium value chain. Electric vehicles, electricity networks and other industrial applications were closely connected with aluminium consumption and raw material imports. Long-haul bauxite shipments from Guinea to China had already become an important component of demand for larger bulk carriers.
@Vincent Vandewalle , Chief Trading Officer of Navios Maritime Partners L.P. , drew a useful distinction: bauxite was already contributing cargoes, while Simandou retained further potential.

That difference affects investment timing. Bauxite cargoes are already part of fleet deployment and earnings. Simandou iron ore volumes depend on the progressive ramp-up of mines, railways, ports and the wider loading system. Vandewalle argued that cargo growth could arrive faster than the corresponding new ships, providing further support for the Capesize market.
Planned capacity must still be distinguished from current shipments. Rio Tinto has stated that, following commissioning and ramp-up, Simandou’s shared infrastructure could support combined exports of up to 120 million tonnes annually from SimFer and WCS. Its latest third-quarter production report indicated that the SimFer mine had reached an annualised production run rate of approximately 10 million tonnes, with a target of reaching a 60 million tonne annual run rate during the second half of 2028.
Those figures describe different project scopes and stages. The combined long-term capacity cannot be treated as cargo already available to the shipping market.
Simandou’s transport impact also depends on which supplies it displaces. If its ore replaces production from other mining regions, global shipment volumes may not increase by the same amount. Loading locations, voyage distances and vessel turnaround could nevertheless change considerably. Fairclough similarly cautioned that bauxite and Simandou involved different demand characteristics, requiring separate assessments of additional cargo and supply substitution.
Vandewalle also suggested that West African cargoes could influence Capesize seasonality. Historically, shipment patterns from Brazil and Australia have helped determine stronger and weaker quarters. A larger West African contribution could alter that distribution. Whether it materially softens the traditional first-quarter weakness will depend on actual production, loading and shipping schedules.
Similar Freight Views, Different Investment Decisions
A favourable cargo outlook did not produce a uniform answer on asset investment.
Fairclough’s approach to Kamsarmax tonnage captured the tension between prospective earnings and acquisition cost. An ageing fleet and relatively limited supply growth supported the operating market, but higher ship prices had raised the investment threshold. Buying at current values required sustained earnings to justify the price. Chartering in vessels offered a different combination of capital commitment and market exposure.
Operating chartered tonnage carries its own risks. Hire commitments, vessel positioning, cargo availability and freight exposure all require management, while forward charter costs can rise with the market. The model relies on the operator’s ability to assemble cargo programmes, deploy ships and control its commitments.
Vandewalle was more positive about investing in newer vessels and newbuildings. He believed that demand fundamentals, particularly in the Capesize segment, could support future earnings. More efficient engines and other performance advantages also strengthened the commercial case for fleet renewal.
Navios continued to evaluate new tonnage while considering longer charters to reduce uncertainty over newbuilding income. Profit-sharing provisions could, where appropriate, preserve some participation in a stronger market.
That approach connects three decisions: the vessel to acquire, the cost of obtaining it and its employment after delivery. A long charter can establish a revenue foundation, but its value depends on the rate, duration, counterparty and contractual allocation of risk. The ship’s condition, remaining debt and residual value when that cover ends also require consideration.
Hashim’s preferred investment segment was Ultramax. Precious Shipping had continued committing capital to these vessels while disposing of smaller and older ships. Fairclough described a comparable direction at Wah Kwong: sales of older Supramaxes, approximately 16 Ultramax newbuildings on order, and efforts to secure longer employment for some earlier orders.
These differences extend beyond a bullish or bearish freight outlook. An owner holding an earlier, less expensive newbuilding contract starts from a different position to an investor buying a high-priced secondhand ship today. An operator chartering in tonnage faces another set of commitments. Similar freight expectations can therefore lead to different commercial actions.
Why Ultramax Keeps Attracting Capital
The interest in Ultramax vessels reflected their range of potential employment.
Hashim focused on the combined value of carrying capacity, speed and consumption, draught and flexibility. For an owner serving steel, grain and multiple minor bulk trades, the ports a vessel can enter, the parcels it can accommodate and its ability to switch between cargoes directly influence its commercial opportunities.
Fairclough likewise described Ultramax as a particularly versatile part of Wah Kwong’s dry bulk fleet. Access to a broad cargo base allows an owner to develop business across customers and regions, while suitable charter arrangements can secure part of the future income.
Relative freight levels between vessel categories create additional opportunities. Coumine described instances of Capesize parcels being split into Panamax shipments. When Supramax rates were comparatively stronger, some cargo interests also considered moving to larger vessels. Demand in each segment could consequently be influenced by conditions in neighbouring categories.
The ability to make that switch depends on port depth, handling capacity, parcel size and the wider logistics chain. A lower freight cost per tonne may be outweighed by restrictions elsewhere in the operation. Assessing an Ultramax investment therefore requires its technical specifications to be considered alongside the owner’s customer base, trading experience and cargo access.
This helps explain why the same vessel type can produce different returns on different platforms. Versatility creates opportunities; the commercial organisation determines how effectively those opportunities become productive voyages.
A Newbuilding Decision Extends Beyond 2030
Coumine raised another question when the discussion turned to future vessel designs: would ships ordered today and delivered several years from now remain suitable for the requirements of the 2030s and beyond?
He also favoured Ultramax, while expressing a preference for preserving alternative fuel options where possible. Hashim acknowledged limitations in the dual-fuel or alternative fuel designs available for the projects his company was considering. Owners’ technical ambitions had to be reconciled with the designs shipyards could actually offer.
Fleet renewal consequently serves two objectives at once: improving present competitiveness and retaining room to respond to future fuel and regulatory developments. Waiting for every technology question to be resolved can delay renewal. Proceeding with investment requires an assessment of what subsequent changes will be practical.
Hashim used Precious Shipping’s fleet renewal to illustrate the operating improvements already achievable. According to his presentation, the company reduced carbon dioxide emissions per cargo tonne-mile by approximately 56% between 2014 and 2025. Over the same period, the fleet remained broadly unchanged at 38 ships, while total carrying capacity increased by approximately 500,000 dwt.
Selling smaller, older ships and acquiring larger, newer and more efficient vessels expanded transport capability while reducing emissions intensity.
The measure concerns emissions per unit of transport work. It does not imply an equivalent reduction in absolute company emissions. It nevertheless demonstrates a measurable outcome from renewal. Fuel efficiency, carrying capacity and port accessibility can affect both the cost and revenue sides of the business.
Chinese shipyards play an important role in that process. Hashim spoke positively about the suitability of Chinese-built bulk carriers for steel cargoes. For an investment expected to operate for more than two decades, delivery quality provides the foundation. Maintenance requirements, actual fuel consumption, cargo suitability, modification options and acceptance in the resale market will continue to shape its value.
Performance After Delivery Matters Just as Much
The discussion also touched on digitalisation and AI, with the panelists describing specific operational applications.
Fairclough said technology had changed how Wah Kwong organised, presented and processed information internally, while its impact on physical asset trading remained more limited. Coumine described the increasing use of platforms that presented market analysis clearly and supported commercial decisions.
Hashim outlined a defined objective for the AI data scientist brought into Precious Shipping: to free up approximately 30% of the time senior management spent dealing with urgent matters, allowing greater attention to important issues. Vandewalle highlighted vessel data, performance optimisation, maintenance planning and the prevention of technical problems.
These investments are closely connected with fleet returns. Information affects market judgement; maintenance affects available trading days; performance management influences fuel consumption; and management’s use of time affects its ability to address risks early.
Strong freight can conceal operating differences. When markets weaken, those differences become more visible in earnings.
Strong Markets Require a View Beyond Delivery
The Capital Link discussion produced no single investment formula applicable to every dry bulk owner.
West African cargo growth, changes in Chinese raw material sourcing and steel exports, and the transportation of coal, grain and minor bulks provided support for demand. Extended delivery schedules and an ageing fleet constrained the speed of supply growth. Improving transport efficiency, further ordering and high acquisition prices nevertheless remained part of the calculation.
Hashim’s positive view of the next four to five years rested on his assessment of demand and supply. Fairclough’s caution over current acquisitions reflected the importance of entry cost. Vandewalle continued to pursue renewal while considering contractual ways to manage income risk. Coumine brought the cargo owner’s concern that transport availability and the future suitability of ships needed to be considered together.
Taken together, these views suggest a disciplined sequence of decisions: establish where cargo will originate and how it needs to move; determine which vessel can serve that task; then assess acquisition cost, employment, financing, maintenance and eventual exit as one investment.
Owners can sell older ships into a strong market while ordering replacements for the future. They can retain spot exposure while securing part of their income under longer contracts. Each decision needs to fit the company’s asset costs, operating capabilities and customer requirements.
Dry bulk retains important sources of support. The next test for owners is whether the choices made today will continue generating returns after new ships arrive, transport efficiency changes and the market moves into another cycle.
READ MORE
 Dry Cargo
Yangzijiang Maritime linked to 4+2 Kamsarmax order
 Dry Cargo
Black Sea Wheat Loadings Plunge 78% as Grain Trade Reroutes
 Dry Cargo
China Merchants Signs $2.8 Billion-Plus Simandou Shipping Deal
 Dry Cargo
Yangzijiang Maritime Orders 4+2 Kamsarmaxes as Watts Energy Expands into Merchant Shipbuilding
 Dry Cargo
Seaspan Enters Newcastlemax Market, with Yangzijiang Set to Build Two Tri-Fuel Ore Carriers
 Dry Cargo
Shipowners Bet on Ultramaxes: 42 Ships for Chinese Yards, Deliveries Stretch into 203
 Dry Cargo
“We Are Buying Ships”: Why Dry Bulk Is Beating Expectations
 Dry Cargo
40 Days from Brazil to China: COSCO SHIPPING Bulk’s New Grain Fleet Takes Shape
 Dry Cargo
Wooyang orders four triple-fuel Newcastlemax bulkers at China’s New Times for Vale contracts
 Dry Cargo